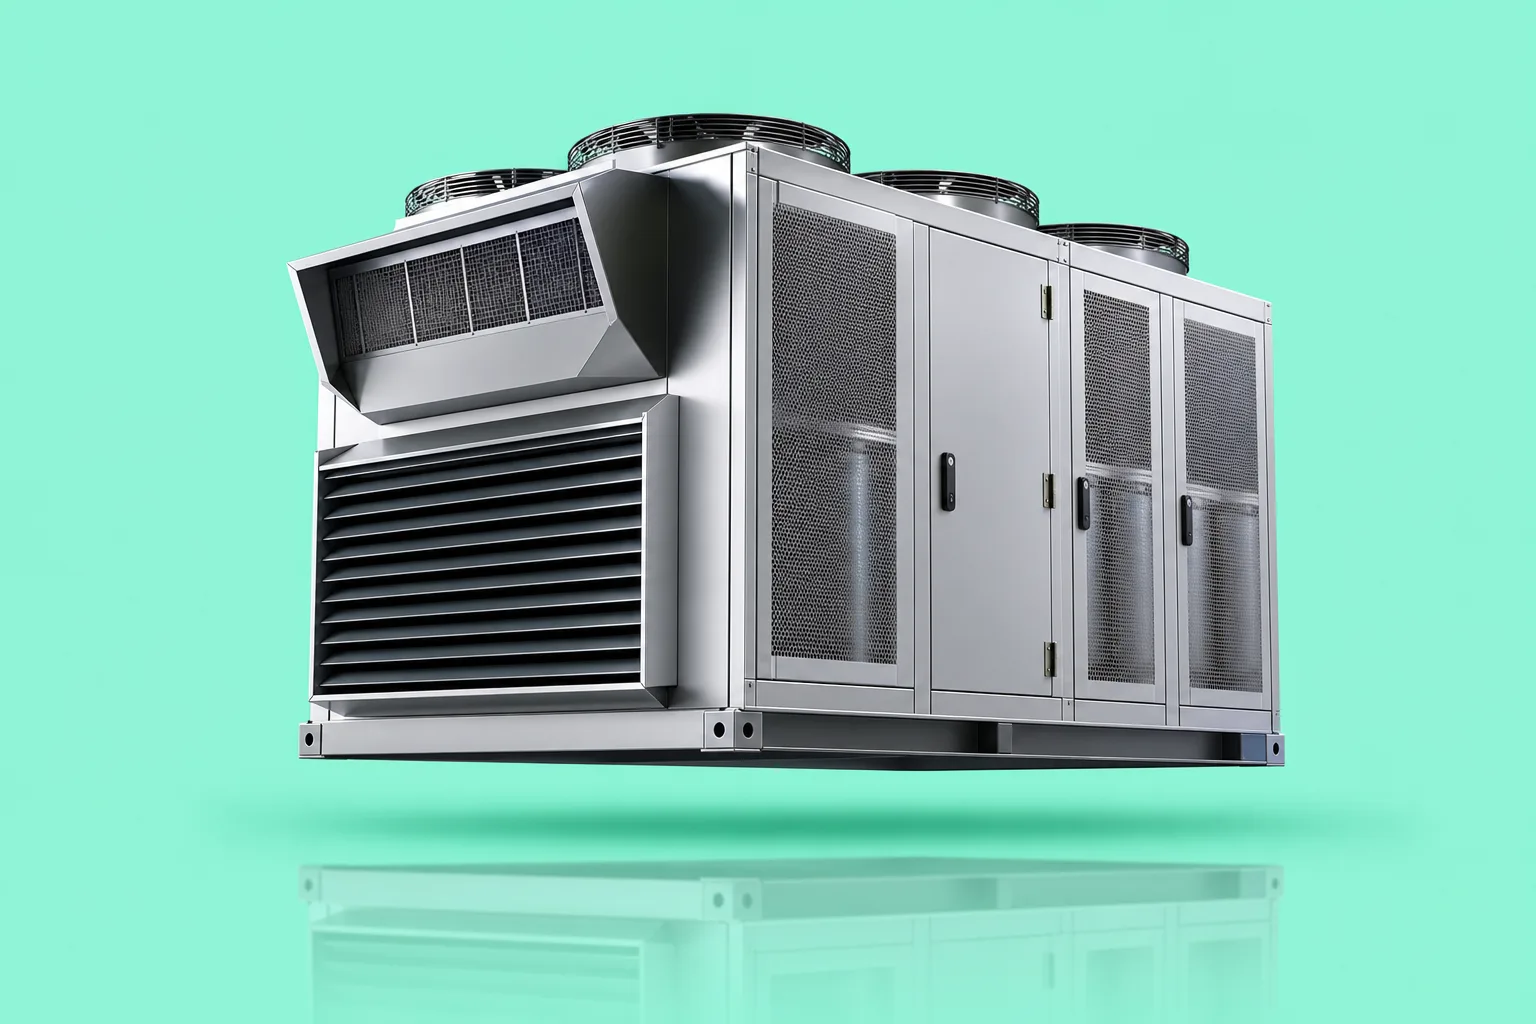
AAON stock surged 23.3% to $77.52 after the company delivered a record third quarter, far ahead of market expectations, and sharply lifted its 2026 revenue growth outlook. The biggest driver was BASX, the company’s data center cooling unit, where sales more than tripled from a year earlier.
The headline numbers were hard to ignore. Third-quarter net sales climbed 84.1% to $707.4 million, while diluted earnings per share rose to $0.83 from $0.37 a year earlier. AAON also raised its 2026 net sales growth forecast to 72%-75%, up from 55%-60%.
For investors, the report changed the near-term narrative around AAON. Concerns about margin pressure, elevated capital spending and weak free cash flow gave way to evidence that AI-related cooling demand is converting into revenue, profits and improved cash generation.
Key Facts
- AAON reported third-quarter net sales of $707.4 million, beating expectations near $599.7 million.
- Diluted EPS came in at $0.83, above consensus estimates of roughly $0.56-$0.57 and up from $0.37 a year earlier.
- BASX-branded sales rose 218.3% to $397.2 million and represented about 56% of total quarterly revenue.
- Total backlog stood at $1.85 billion on September 30, including $1.36 billion tied to BASX.
- The company lifted its 2026 sales growth outlook to 72%-75%, implying full-year revenue of about $2.48 billion to $2.52 billion.
AAON stock and BASX data center cooling
The central story behind the AAON stock rally is the speed at which BASX is scaling. What had been a traditional commercial HVAC business is increasingly becoming a supplier to data center and liquid cooling projects tied to AI infrastructure buildouts. BASX sales reached $397.2 million in the quarter, overtaking the legacy AAON-branded business and shifting the company’s revenue mix toward higher-growth end markets.
Liquid cooling is an especially important piece of that transition. BASX liquid cooling sales increased 255.6% to $165.5 million in the quarter, and management indicated demand remains strong as high-density computing deployments expand. That matters because cooling has become a critical bottleneck in AI data centers, and suppliers with proven manufacturing capacity and custom-engineering capabilities are in a relatively small field.
The quarter also suggested that AAON is moving beyond a pure capacity-build story. Investors had worried that aggressive expansion would dilute margins and consume cash before new plants became productive. Instead, the latest results showed margin recovery, positive quarterly free cash flow and a backlog still large enough to support elevated growth into 2027. That combination helped offset concerns tied to accounting restatements and internal controls.
AAON’s latest quarter showed that data center cooling demand is no longer just a backlog story; it is now flowing through to revenue, earnings and cash flow at a much faster pace than investors had modeled.
Why the margin trend mattered
Beyond the revenue beat, margins were a major focus. Gross margin improved sequentially to 26.7% from 24.3% in the second quarter, suggesting the BASX ramp is becoming more efficient as volume rises. Operating income more than doubled to $100.0 million, a record for the company, while adjusted EBITDA reached $127.2 million.
That sequential improvement is important because it addresses one of the market’s biggest doubts. New facilities, including the Memphis site, have been operating below full utilization, which has created overhead drag. If utilization continues to improve over the next several quarters, investors could see additional earnings leverage even if revenue growth moderates from its current pace.
Implications for Investors
For shareholders, AAON now sits at the intersection of two competing forces: exceptional growth tied to AI infrastructure and ongoing execution risk tied to internal controls and capital deployment. On the bullish side, the company has a large contracted backlog, more than $2 billion of annual BASX capacity, and improving free cash flow as capital spending begins to normalize. Those factors support the case for continued earnings growth in 2027.
At the same time, investors should not ignore the risks. AAON restated first- and second-quarter results and disclosed a material weakness in internal control over financial reporting. Even though the revisions were largely timing-related and increased first-half revenue and EPS overall, remediation may take several quarters. Any further accounting issues, regulatory scrutiny or litigation could pressure valuation.
There is also concentration risk. BASX is increasingly tied to data center spending, particularly projects linked to AI computing demand. If hyperscale customers slow orders, financing conditions tighten or data center development faces local political pushback, AAON’s growth outlook could come under pressure. Investors should watch fourth-quarter bookings, gross margin progression, cash flow and any updates on control remediation as the next key markers.
AAON has clearly reset market expectations with a record quarter and a much stronger growth outlook. The next test is whether the company can sustain BASX momentum while proving that operational gains are durable and governance issues are contained.