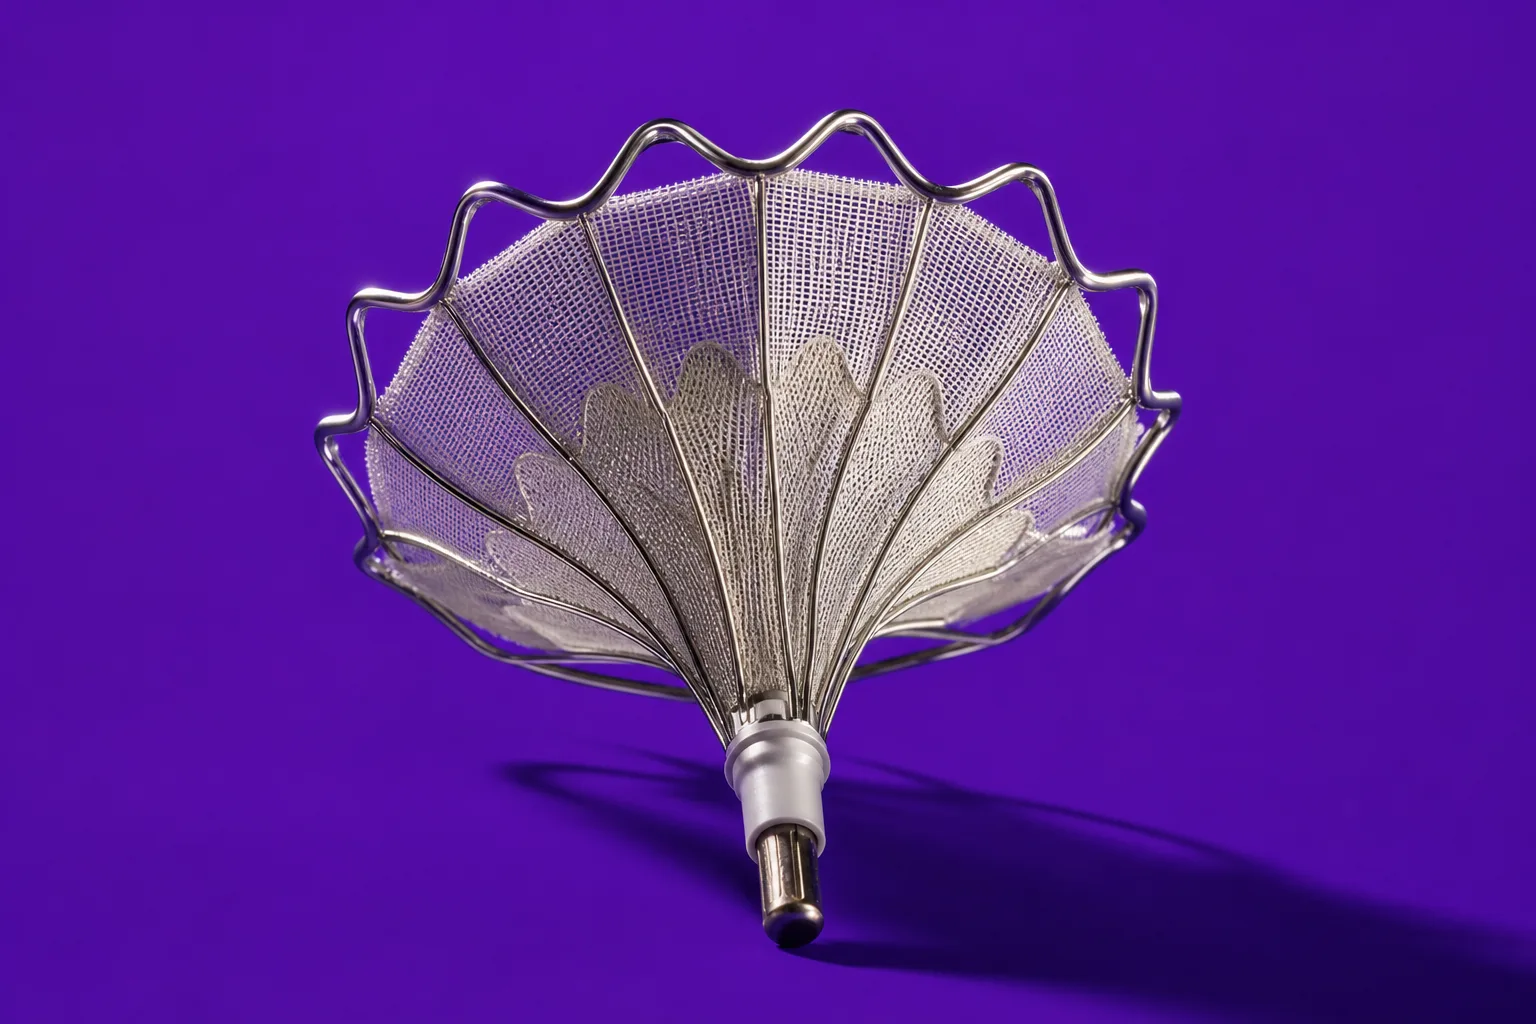
Boston Scientific stock fell sharply after the medical device maker lowered its 2026 outlook for the third time this year, pushing shares briefly below a prior 52-week low before buyers stepped in. The company trimmed full-year adjusted earnings guidance to $3.16 to $3.18 a share and now expects about 4.25% sales growth for 2026.
The market reaction was immediate. Shares dropped as much as 13% to $39.40 before recovering part of the loss and trading near $43.26 late in the session. The selloff reflected more than a one-quarter miss: investors were responding to a broader slowdown in two of Boston Scientific’s most important growth engines, WATCHMAN and electrophysiology.
The new forecast also raised concern about 2027. Management indicated the company will be challenged to grow sales and adjusted EPS next year excluding the pending Penumbra acquisition, reinforcing the view that the current downturn may last longer than many investors expected.
Key Facts
- Boston Scientific reported third-quarter 2026 net sales of $5.138 billion, up 1.5%, with adjusted EPS of $0.73.
- The company cut full-year 2026 adjusted EPS guidance to $3.16 to $3.18 from $3.28 to $3.32.
- Fourth-quarter guidance calls for net sales to decline 1% to 3% and adjusted EPS of $0.77 to $0.79.
- An August 25 cyberattack reduced third-quarter sales by about $150 million and cut adjusted EPS by $0.07.
- WATCHMAN revenue fell 6% and electrophysiology sales declined 5% in the quarter.
Boston Scientific Stock
The core issue for Boston Scientific is that a temporary disruption exposed a deeper operating slowdown. The cyberattack that shut plants and distribution centers for eight days clearly hurt results, but it did not fully explain the magnitude of the reset. Third-quarter revenue growth of 1.5% came in below the company’s prior 3% to 5% target, while adjusted EPS of $0.73 missed both management’s earlier range of $0.80 to $0.82 and market expectations.
More importantly, the company’s highest-profile franchises lost momentum at the same time. WATCHMAN, its left atrial appendage closure device, posted a 6% sales decline, while electrophysiology revenue fell 5%. Those businesses had been central to Boston Scientific’s premium valuation during its high-growth phase. When higher-margin growth categories slow, the damage reaches both revenue and profitability.
That dynamic is already visible in margins. GAAP gross margin fell to 66.7% from 69.9% a year earlier, while adjusted gross margin slipped to 68.0% from 71.0%. A weaker mix, cyber-related inefficiencies and pricing pressure in China added to the strain. For investors, this matters because the company is no longer being judged as a double-digit grower. It is being revalued as a business facing slower organic growth, rising execution risk and reduced forecasting credibility.
Boston Scientific’s latest reset suggests the cyberattack hurt the quarter, but the deeper challenge is the simultaneous slowdown in WATCHMAN and electrophysiology that may continue into 2027.
Why WATCHMAN and EP Matter Most
WATCHMAN and electrophysiology have outsized strategic importance because they helped define Boston Scientific’s growth story for several years. WATCHMAN revenue had climbed to nearly $2 billion in 2025, but growth faded rapidly in 2026 as standalone procedures weakened. Management indicated the franchise could reach its maximum decline in 2027 before stabilizing later.
Electrophysiology has followed a similar pattern. After rapid adoption of the FARAPULSE platform, growth slowed and then turned negative as competitors expanded their own pulsed field ablation offerings. Boston Scientific’s U.S. electrophysiology sales fell 8% in the quarter, highlighting market-share pressure in one of medtech’s most competitive categories. Because these businesses also carry attractive margins, their slowdown has a disproportionate impact on earnings quality.
Implications for Investors
For shareholders, the immediate question is whether the selloff has already priced in the bad news. At roughly $43.26, Boston Scientific trades at about 13.6 times the midpoint of its revised 2026 adjusted EPS guidance, near the low end of its forward valuation range over the past five years. That may attract value-oriented investors looking for a stabilization story rather than a near-term growth rebound.
Still, risks remain substantial. Management has now reduced 2026 expectations three times, which weakens confidence ahead of January guidance for 2027. Investors will be watching whether lost procedures return after the cyber disruption, whether electrophysiology share erosion slows, and whether WATCHMAN demand stabilizes. A further deterioration in these areas could pressure both earnings estimates and valuation.
The pending Penumbra acquisition is another key variable. The approximately $14.5 billion transaction is expected to close in early 2027 and could provide an important external growth driver in thrombectomy and stroke intervention. But the deal also introduces financing costs, integration risk and greater dependence on execution at a time when Boston Scientific is already managing supply-chain recovery, restructuring and competitive product launches.
Technically, the stock’s rebound from $39.40 suggests some investors see support near the low $40s. Even so, the market appears to be waiting for firmer evidence that the business can build a base between $40 and $47 and regain visibility on earnings power. A sustained move back toward $46 to $47 would indicate improving confidence, while another break below $39.40 would likely reopen downside risk.
Boston Scientific enters the next reporting cycle with a lower valuation but a more demanding burden of proof. January’s 2027 guidance, the pace of recovery in core franchises and progress on the Penumbra close will likely determine whether the stock has found a durable bottom or is still repricing to a slower-growth future.