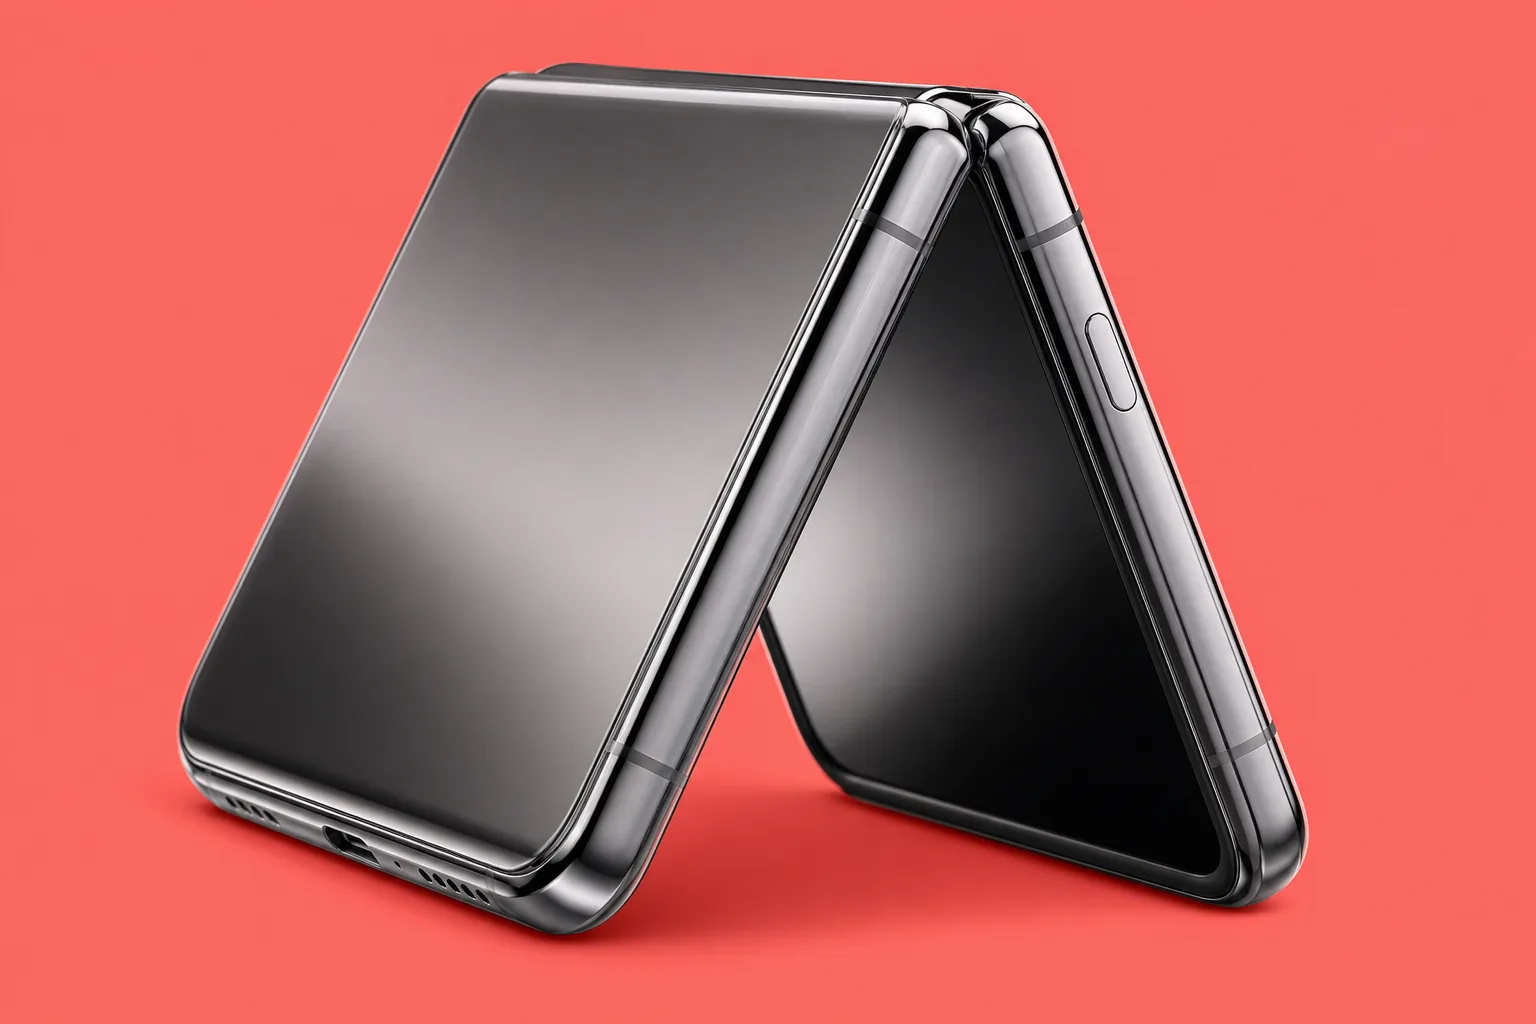
Apple’s long-anticipated foldable iPhone is expected to headline the company’s September 9 product event in Cupertino, but early supply-chain signals suggest the launch could be constrained by production bottlenecks. Initial output has reportedly been running at only a few hundred units per day in late August, a pace that raises doubts about near-term availability.
The foldable iPhone, widely expected to be branded as the iPhone Ultra or a similar premium nameplate, could carry a starting price above $2,000. Estimates in circulation place the device between roughly $2,199 and $2,499, positioning it as Apple’s most expensive mainstream smartphone and a major test of consumer demand for ultra-premium hardware.
For investors, the central question is whether high pricing and a richer product mix can compensate for lower shipment volumes, especially as Apple enters a leadership transition and faces fresh competition in foldable devices.
Key Facts
- Early foldable iPhone production was reportedly only a few hundred units per day in late August despite a broader annual target of 8 million to 10 million units.
- Expected pricing for the foldable iPhone ranges from about $2,199 to as high as $2,499, far above the current Pro lineup.
- Preorders for the foldable model may slip into the fourth quarter even if the device is unveiled on September 9.
- Projected iPhone 18 Pro and Pro Max builds are 73 million across fiscal Q4 2026 and fiscal Q1 2027, versus an estimated 67.7 million for comparable prior-year models.
- Apple shares were up 17.7% year to date as of the latest Friday close, while the average 12-month analyst target implied about 3% upside.
Foldable iPhone
The expected introduction of Apple’s first foldable iPhone marks one of the company’s most significant hardware category expansions in years. The device is rumored to feature a 5.5-inch outer display and a 7.8-inch inner screen, along with an A20 Pro chip, a C2 modem, a titanium frame, and a side-mounted Touch ID system. At an estimated thickness of around 4.5mm when opened, the product appears designed to compete on engineering sophistication as much as on brand appeal.
What matters most, however, is not the spec sheet but the launch mechanics. A production run of only a few hundred units per day is difficult to reconcile with annual output goals in the millions unless manufacturing ramps sharply in a very short period. Reports of an extra August trial run suggest Apple is prioritizing quality control over speed, which is consistent with the company’s history of protecting the user experience on first-generation hardware.
The stakes extend beyond one device. Apple is expected to unveil the foldable alongside the iPhone 18 Pro and iPhone 18 Pro Max, both of which are also rumored to receive meaningful price increases. If the foldable is supply-constrained and the rest of the lineup becomes more expensive, Apple may preserve revenue and margins through pricing and mix, but unit growth could remain under pressure. That matters for suppliers, carriers, and investors focused on shipment trends rather than headline product excitement.
Apple’s foldable iPhone may generate strong interest, but constrained supply and a price above $2,000 could turn its debut into a margin story before it becomes a volume story.
Pricing, timing and the broader product cycle
Analysts are modeling a more premium-heavy launch cycle. One widely cited scenario assumes the iPhone 18 Pro rises by $150 to $1,249, the Pro Max climbs by $200 to $1,399, and the foldable iPhone enters at about $2,199. That pricing structure would push average selling prices higher even if total unit builds decline.
Current expectations point to total iPhone 18 builds of around 80 million, compared with roughly 91 million in the prior year, implying an approximate 12% drop in unit volume. Part of that decline appears tied to lineup composition, including the absence of a standard iPhone 18 base model in some forecasts. In that context, the foldable becomes strategically important not because it will sell in massive quantities immediately, but because it could lift average revenue per device and reinforce Apple’s premium positioning.
The timing also matters. If preorders for the foldable shift into the fourth quarter, the launch would resemble earlier staggered iPhone rollouts where announcement and availability did not align. Such delays can affect quarterly revenue recognition, near-term sentiment, and channel planning, even if demand remains intact.
Implications for Investors
For shareholders, the near-term setup is mixed. On one hand, a foldable iPhone gives Apple a new premium category that could deepen its hold on high-end consumers and open a path to higher average selling prices. On the other, first-generation hardware often carries execution risk, and production constraints can limit upside in the first several quarters.
Investors should watch three variables closely: ramp speed, pricing acceptance, and gross margin impact. If manufacturing improves rapidly after the September 9 event, concerns about availability could fade. If consumers absorb price increases across the Pro lineup, Apple may offset softer units with stronger revenue per device. But if sticker shock weighs on demand and supply remains tight, the market could focus on weaker shipment trends rather than innovation.
Competition is another factor. Huawei is set to release a new trifold smartphone on September 7, just ahead of Apple’s event. While Apple’s customer base is unusually loyal, the foldable segment is no longer experimental. That raises the bar for differentiation in design, durability, battery life, and software integration. It also means Apple’s first move into the segment will be judged against products that have already had multiple generations to mature.
Historically, Apple’s September iPhone events have not always been immediate catalysts for the stock. Average share performance on announcement day over the past five years has been modestly negative, with a weaker five-day follow-through. With the shares already up 17.7% year to date and consensus price targets implying limited additional upside, the burden may be on execution rather than surprise.
The September 9 event will clarify whether Apple’s foldable strategy is ready for scale or still in controlled rollout mode. The long-term opportunity is significant, but the first signals investors receive may come from supply discipline and pricing power rather than headline demand.