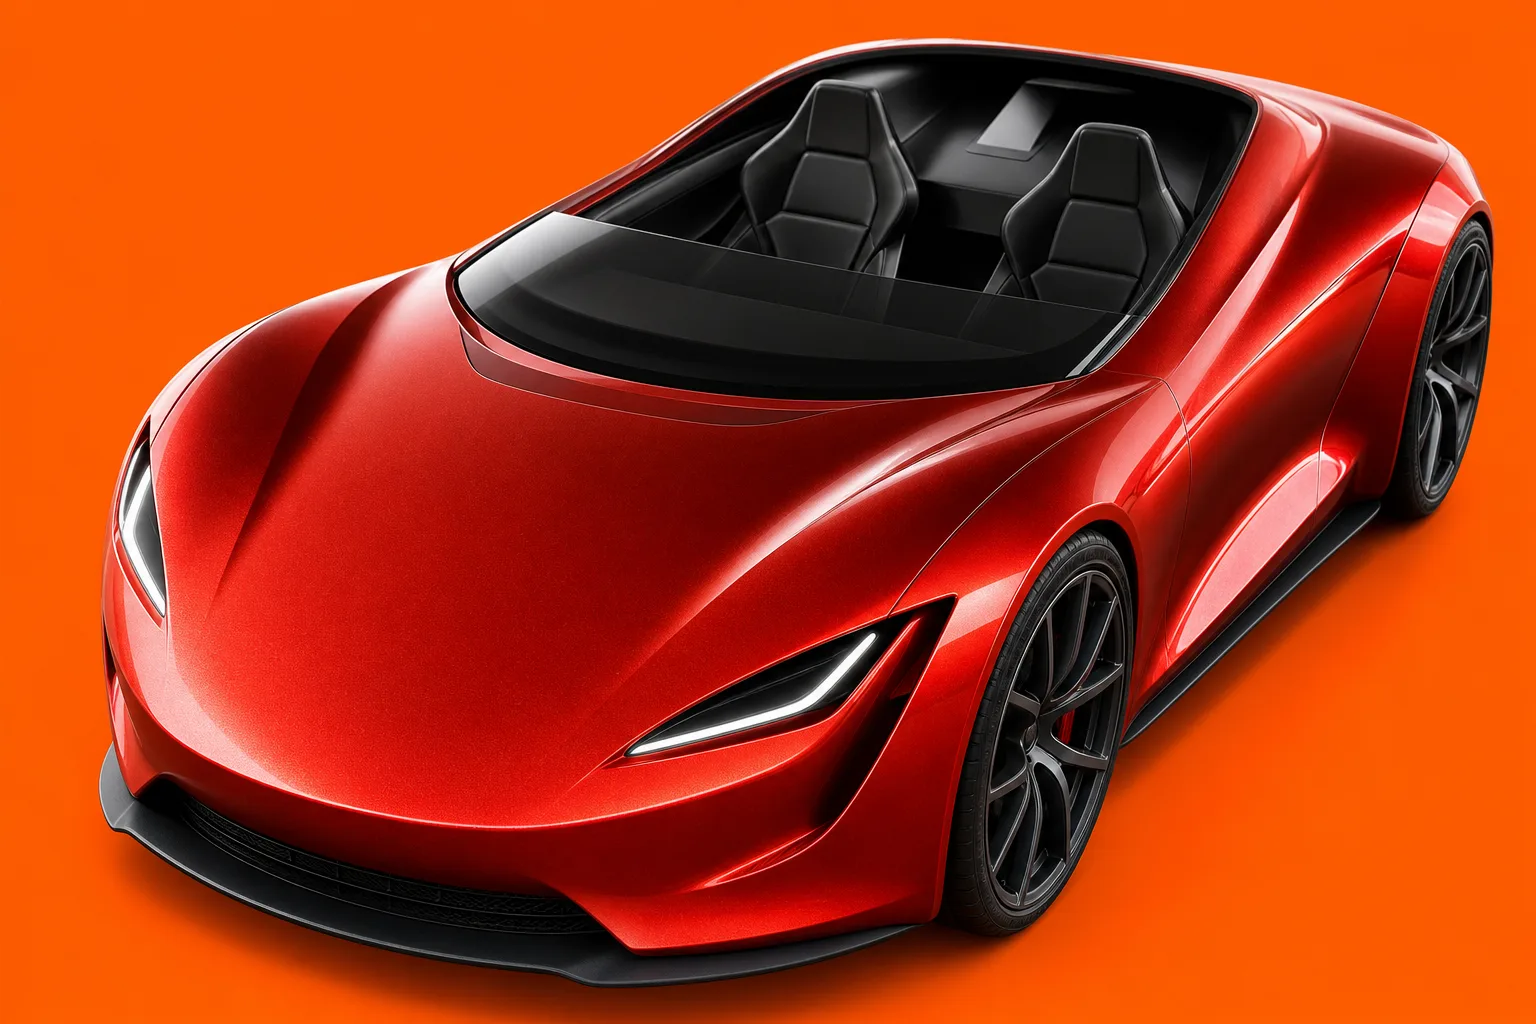
Tesla stock lost momentum quickly after an initially strong reaction to the company’s Roadster reveal, underscoring how little patience the market has for spectacle without near-term financial impact. By 11:10 a.m. ET, shares were trading at $359.60, down $2.84, or 0.78%, and below the prior close of $362.44.
The reversal was sharp. Tesla had climbed as much as 5.4% in premarket trading to roughly $382 after the event at SpaceX’s Texas facility, only to slide steadily after the opening bell. From the premarket high to the session low of $359.29, the stock shed nearly $23 a share in less than three hours.
For investors, the message was straightforward: the Roadster generated attention, but the next meaningful move in Tesla stock is more likely to come from third-quarter earnings on October 21, especially any update on automotive margins, free cash flow and demand trends in China.
Key Facts
- Tesla stock traded at $359.60 at 11:10 a.m. ET, down 0.78% and below the prior close of $362.44.
- Shares rose as high as roughly $382 in premarket trading, a gain of about 5.4% before the rally faded.
- Third-quarter deliveries totaled 486,532 vehicles, exceeding the 24-analyst consensus of 461,974 by 24,558 units.
- Tesla reports third-quarter earnings after the close on October 21, with consensus calling for about $0.43 to $0.45 in EPS on roughly $27.8 billion to $27.9 billion in revenue.
- The stock is down 20.0% year to date and sits 27.9% below its 52-week high of $498.83.
Tesla Stock
The trading action showed a classic gap fade: buyers pushed Tesla higher overnight on headline excitement, but regular-session investors sold into strength. That kind of pattern often suggests traders see the news as interesting rather than financially material. In Tesla’s case, the Roadster is a brand and engineering showcase, not a product expected to influence revenue or earnings soon.
The reveal itself included ambitious claims, including a 0-60 mph time of 0.81 seconds for one version and a production target in 2028. Tesla also opened reservations with a $50,000 commitment structure, made up of a $5,000 deposit and a $45,000 wire transfer due within 10 days. What was missing mattered more for valuation: no final pricing, no confirmed production site and no evidence the model will contribute meaningfully to near-term cash flow.
Broader market conditions added pressure. The Nasdaq Composite fell 1.11% to 26,416.15, while other high-growth technology names also traded lower. With Tesla’s five-year beta near 1.92, a weak session for risk assets tends to amplify moves in the stock. That dynamic likely accelerated selling once the premarket enthusiasm faded.
Tesla’s Roadster reveal may have energized the brand, but the market is still demanding proof of margin recovery and disciplined execution.
Why the October 21 earnings report matters more
The strongest near-term fundamental argument for Tesla is its third-quarter delivery performance. The company delivered 486,532 vehicles, up 1.3% from the second quarter and well above consensus expectations. Tesla also delivered more vehicles than it produced for a second straight quarter, helping clear earlier inventory buildup and potentially reducing the need for aggressive discounting.
But deliveries alone do not settle the core debate. In the second quarter, Tesla posted $28.24 billion in revenue but adjusted earnings per share of only $0.33, missing the $0.50 consensus. Automotive gross margin excluding regulatory credits fell to 16.3% from 19.2% in the prior quarter. Investors now need to see whether stronger delivery volume translated into better profitability, especially as Chinese discounts and spending on AI, robotaxis, Optimus and Semi capacity continue to weigh on costs.
Implications for Investors
For portfolio managers and retail investors alike, Tesla remains a stock driven by expectations rather than current earnings power. At a market value of about $1.42 trillion and a trailing price-to-earnings ratio above 300, the shares are priced for major success in businesses beyond core vehicle manufacturing. That leaves little room for another margin disappointment.
There are still clear positives. Tesla’s balance sheet remains strong, with $43.52 billion in cash and investments and access to $30 billion in new credit lines. Energy storage deployment reached 13.7 GWh in the third quarter, extending one of the company’s most consistent growth segments. Inventory normalization could also support gross margin if pricing stabilizes.
The watch-points are equally clear. China remains a mixed picture, with Shanghai exports surging but domestic retail sales under pressure. Regulatory credit revenue has declined sharply from year-earlier levels, reducing a high-margin earnings buffer. Meanwhile, planned capital expenditures of at least $25 billion raise the stakes for execution in Cybercab, Semi and Optimus. Investors should pay closest attention to automotive gross margin excluding credits, free cash flow, management’s spending outlook and any quantified update on robotaxi commercialization.
If Tesla can show margin improvement and a credible path to funding its growth agenda without prolonged cash burn, the stock may regain footing after the post-Roadster fade. If not, the failed breakout near $382 could leave earnings as the next catalyst for renewed downside.